| B | C | |
|---|---|---|
| 149 | SELLER ANCHOR TO IOI BRIDGE | |
| 150 | Seller-basis EV anchor | 4,8191 |
| 151 | Less: transaction costs, severance, VPPA gains and interest income (EBITDA quality) | (172) |
| 152 | Less: power cost not recovered | (157) |
| 153 | Less: contracted-term discount | (233) |
| 154 | Less: development exposure | (36) |
| 155 | IOI midpoint before rounding | 4,2212 |
- 119.2x the seller's $224.0M adjusted EBITDA, plus $508M spent on buildings under way. The 19.2x is the six campus appraisals' multiple and values the operating buildings only
- 2Rounded to $25M, Compound's indication is $4,225M, about $0.6B below what the CIM implies
You are the associate on the buy side. The banker, Kingsmill & Co., has sent the CIM for Project Voltaic: the sale of 100% of Ironvale Digital Infrastructure, a US data center developer and operator with 220 MW of commissioned capacity in six markets. The CIM shows $412.0M of FY25 revenue and $224.0M of adjusted EBITDA. The process letter of June 12, 2026 asks for a single enterprise value by July 23.
Before anyone prices the deal, your job is to test the CIM against everything else in the data room: the audited accounts, the executed leases, the power data and the construction budgets. This page takes that check one step at a time, each step run in Compound. The answer at the end: four of the CIM’s claims do not survive the room, and Compound indicates $4,225M, about $0.6B below what the CIM’s own numbers imply.
A confidential information memorandum (CIM) is the sell-side banker’s book on a company for sale, sent to buyers under an NDA after the teaser. The investment teaser is the anonymous one or two pages that come first. An offering memorandum (OM) is the same document under another name, common in larger processes and in real estate, where the broker’s OM carries a rent roll and a T12 (see the rent roll and real estate pro forma examples). A CIM nearly always holds an executive summary, investment highlights, operations, customers, market, management, historical financials with adjusted EBITDA, projections and an appendix.
Ironvale Digital Infrastructure and Project Voltaic are fictional: the company and its data room are the open data room of PE Bench, published under CC-BY-4.0. Everything Compound produced on this page is real: the workbook, tear sheet, IOI letter and slide come from one Compound run on that room, quoted unedited apart from excerpts.
CIM tear sheet: what the book says, on one page
The first step boils the CIM down to one page a partner can read in five minutes, every figure cited to its page.
Project Voltaic: buy-side tear sheet
Business. Founded in 2014 and headquartered in Dallas, TX, Ironvale develops, owns and operates hyperscale and enterprise colocation data centers in six US markets (Northern Virginia, Dallas, Phoenix, Atlanta, Columbus, Reno). It has 220 MW of commissioned critical IT capacity across 11 buildings, 96 MW under construction and a ~400 MW land bank. Three hyperscale anchors provide 56% of ABR and 140 enterprise customers the rest; the company has 385 employees. Halcyon and the other equityholders are selling 100% of the equity through Kingsmill & Co.
- FY25 total revenue: $412.0M Audited FS FY25 (2.03) p4
- FY25 NOI: $246.6M Audited FS FY25 (2.03) p4
- FY25 adjusted EBITDA, seller: $224.0M CIM (11.02) p3
- Annualized base rent: $305.0M CIM (11.02) p5
- Occupancy at 31-Mar-26: 91.9% CIM (11.02) p6
- Capacity in flight, budget / spent: $988M / $508M CIM (11.02) p18
- Net debt and debt-like, bank / seller / buy-side: $1,485M / $1,506.9M / $1,584.0M CIM (11.02) p32; Sell-side QoE (11.04) p16; deal team
Read as written, the CIM sells a long-dated, triple-net platform that funds its own growth. It claims a 6.9-year weighted average lease term (WALT), power passed through to tenants at cost and no new equity needed to finish the buildings under way.
Takeaway: so far the tear sheet tells the seller’s story, and the next step tests it against the room.
How to tie out a CIM against the data room
The second step sets each claim in the CIM against the document in the room that can prove or disprove it.
Compound’s CIM Tie-Out tab tests 24 claims. Revenue, NOI and occupancy tie to the audited accounts and the rent roll. These are the four contradicted claims that move the bid most.
| D | E | F | G | H | I | M | |
|---|---|---|---|---|---|---|---|
| 6 | CIM claim | CIM page | CIM figure | Room figure | Unit | Difference | EV at stake ($M) |
| 9 | Adjusted EBITDA of $224.0M presented as NOI less G&A | p29 | 224.0 | 212.81 | $M | (11.2) | 105 |
| 12 | Wholesale leases triple-net in substance; metered power passed through at cost ($84.2M FY25) | p23 | 84.2 | 92.42 | $M | 8.2 | 157 |
| 13 | Portfolio WALT of 6.9 years, ABR-weighted at 31-Mar-26 | p3, p5, p24 | 6.9 | 4.03 | years | (2.9) | 233 |
| 20 | No new equity required to complete capacity in flight | p18 | 0.0 | 365.04 | $M | 365.0 | 365 |
- 1NOI less G&A is $212.8M. The $11.2M gap is other income the CIM table leaves out. Compound removes the $5.4M of VPPA gains and interest on cash, worth $105M at 19.2x, and keeps $5.8M of recurring fees
- 2Interval data put FY25 utility cost at $92.4M against $84.2M billed to tenants. About $8.2M a year is absorbed by the company and missing from EBITDA
- 3The executed hyperscale leases expire 2028 to 2032. The rent roll shows 2034 to 2037, and no amendment in the room explains the change
- 4$480M of spend remains on the buildings under way against $115M of undrawn construction facilities
The lease term is the finding a reader of the CIM alone could never make. The rent roll and the lease abstracts agree with the CIM. Only the executed leases, in a separate folder, show the hyperscale tenants’ terms ending four to seven years earlier. On those dates, hyperscale WALT is 4.6 years, not 9.7, and 31.8 MW carrying about $44M of rent rolls by FY28.
Takeaway: the room contradicts the CIM on earnings, power, lease term and funding, and in the bid they take about $597M off the value the CIM implies.
Adjusted EBITDA: $224.0M in the CIM, $206.9M for a buyer
The third step rebuilds the seller’s adjusted EBITDA one add-back at a time and sets out what a buyer would pay for.
| B | C | D | E | |
|---|---|---|---|---|
| 6 | Item | Seller FY25 | Buyer FY25 | Buyer view |
| 10 | Reported EBITDA ($M) | 219.1 | 219.1 | |
| 11 | (+) Transaction & process costs | 4.8 | 1.91 | Reduce |
| 12 | (+) Storm repair, June 2025 hail event (DFW I) | 1.1 | 1.1 | Accept |
| 13 | (+) Severance, two commercial roles | 0.6 | 0.02 | Reject |
| 14 | (-) Insurance recoveries received (DFW I storm) | (1.0) | (1.0) | Accept, query |
| 15 | (-) One-time property tax refund (PHX I appeal) | (0.6) | (0.6) | Accept |
| 16 | Adjusted EBITDA, seller definition ($M) | 224.0 | 220.5 | |
| 17 | (-) VPPA settlements and interest income (embedded in seller figure) | 0.0 | (5.4)3 | Cut |
| 18 | (-) Power cost not recovered from tenants | 0.0 | (8.2)4 | Reduce (new) |
| 19 | Buyer adjusted EBITDA ($M) | 224.0 | 206.95 | |
| 20 | Difference, buyer vs seller | (17.1) |
- 1Only the November and December spend follows the Board's 19-Nov-25 authorization of a sale review. The $2.88M of pre-sale readiness spent from May to September is cut
- 2Rejected: the two commercial roles are being rehired, so the saving does not recur
- 3$2.20M of VPPA settlements and $3.24M of interest on cash, which goes in a cash-free deal. The $5.76M of development and management fees stays in
- 4Power cost not recovered from tenants, from the interval data
- 5Buyer adjusted EBITDA, the base Compound capitalizes
Compound accepts the storm repair and tax refund items, with a query on the insurance recovery. From the CIM’s $224.0M it deducts $2.9M of pre-sale readiness costs spent before the Board authorized a sale, the $0.6M severance add-back, because the roles are being rehired, and $5.4M of VPPA gains and interest on cash, which leaves $215.1M. It then deducts the $8.2M of power cost the tenants do not pay, which gives $206.9M. The $5.8M of development and management fees stays in, because it recurs every year. The adjusted EBITDA page goes through each kind of add-back, and the financial due diligence example carries the full buy-side work.
Takeaway: a buyer’s adjusted EBITDA is $206.9M, $17.1M below the CIM’s $224.0M.
Management questions, ranked by the value at stake
The fourth step turns each contradiction into a question for management and the first document request that would settle it.
| B | C | D | F | |
|---|---|---|---|---|
| 6 | # | Topic | Question | Value at stake ($M) |
| 7 | 1 | Contracted term | The executed wholesale leases expire 2028 to 2032 (Exhibit A), but the rent roll and lease abstracts show current terms to 2034 to 2037. Which signed amendments or phase supplements extended each phase, and when? | 233 |
| 8 | 2 | Power pass-through | Interval data estimate FY25 utility cost at $92.4M against $84.2M billed to tenants, yet the P&L shows power cost equal to reimbursements. Where is the $8.2M booked, and how much is house load, vacancy or the 1.35 PUE cap? | 157 |
| 9 | 3 | EBITDA quality | Adjusted EBITDA includes $11.2M of other income per the management accounts ($11.1M in the audited statements). We keep the $5.8M of development and management fees as recurring; which contracts support them, and why are $5.4M of VPPA gains and interest income in adjusted EBITDA when the CIM bridge omits the line? | 105 |
| 10 | 4 | Development funding | Remaining spend on PHX II and ATL II is $480M against $115M of undrawn construction facilities. How is the gap funded before closing, and does any of it fall to the buyer? | 365 |
Each question names the document that would answer it. The first asks for every executed amendment and phase supplement for the 12 hyperscale leases, reconciled to the rent roll. If those amendments exist, the lease-term discount goes away.
Takeaway: the four questions that move the bid go to management first, and the lease amendments alone are worth $233M.
The IOI: $4,225M, with no banker guidance to bid against
The last step prices the bid and writes the letter and the committee slide from the same workbook.
The process letter gives no price or multiple guidance. It asks for a single cash-free, debt-free value and says any range will be read at its low end. So Compound set the bid against what the room implies. The six campus appraisals imply 19.2x FY25 EBITDA before other income, a multiple that values the operating buildings only, with no platform premium and no development pipeline. On the seller’s $224.0M plus the $508M already spent on buildings under way, it gives about $4.82B. Compound applies 17.7x to 18.5x to the buyer’s $206.9M, a discount for the shorter lease term, adds the buildings under way at cost and deducts the PHX II cost overrun and the unbudgeted $18M DFW chiller. That gives a range of $4,144M to $4,299M. The size of that discount, 0.75x to 1.5x, is Compound’s own judgment, set as an input in the Workings tab.
1. Headline value
We indicate an enterprise value of $4,225 million for 100% of the equity interests of the Company. This is a single value, as the process letter requests. It equals 18.9x the FY25 adjusted EBITDA of $224.0 million presented in the CIM, 20.4x our diligence view of FY25 adjusted EBITDA of $206.9 million and 19.4x our view of LTM March 2026 adjusted EBITDA of $217.9 million.
2. Basis of valuation and key assumptions
Earnings base. FY25 adjusted EBITDA of $206.9 million. From the CIM’s $224.0 million we deduct $2.9 million of pre-sale readiness costs incurred before the Board’s November 2025 authorization, the $0.6 million severance add-back (the roles are being rehired) and $5.4 million of VPPA settlement gains and interest income, which leaves $215.1 million; we then deduct $8.2 million of power cost that interval data show is not recovered from tenants. Development and management fees of $5.8 million stay in, as they recur every year.
Reference multiple. The six operating-campus appraisals total $4,095 million as is at March 31, 2026, or 19.2x FY25 EBITDA before other income of $212.8 million (audited NOI less G&A). That multiple values the operating buildings only, with no platform premium and no development pipeline. We apply 17.7x to 18.5x because the executed hyperscale leases in the clean room expire between 2028 and 2032, which puts contracted portfolio WALT at about 4.0 years rather than 6.9 years. With capacity in flight added (next point), the enterprise value range is $4.14 billion to $4.30 billion.
Capacity in flight. PHX II and ATL II are valued at cost spent to March 31, 2026 of $508 million, less $17.6 million to restore PHX II contingency and cover the unaccrued HVAC claim, and less the $18 million DFW I-A chiller replacement that the long-range plan does not fund.
Upside to our value. Executed amendments supporting the rent-roll lease terms would add up to about $233 million, and documented power cost recovery up to about $157 million.
3. Net working capital and debt-like items
We put net debt and debt-like items at $1,584.0 million, against $1,506.9 million in the QoE at December 31, 2025. On these figures our indication implies an equity value of about $2,641 million before the working capital true-up.
Compound put the whole review on one slide for the investment committee.
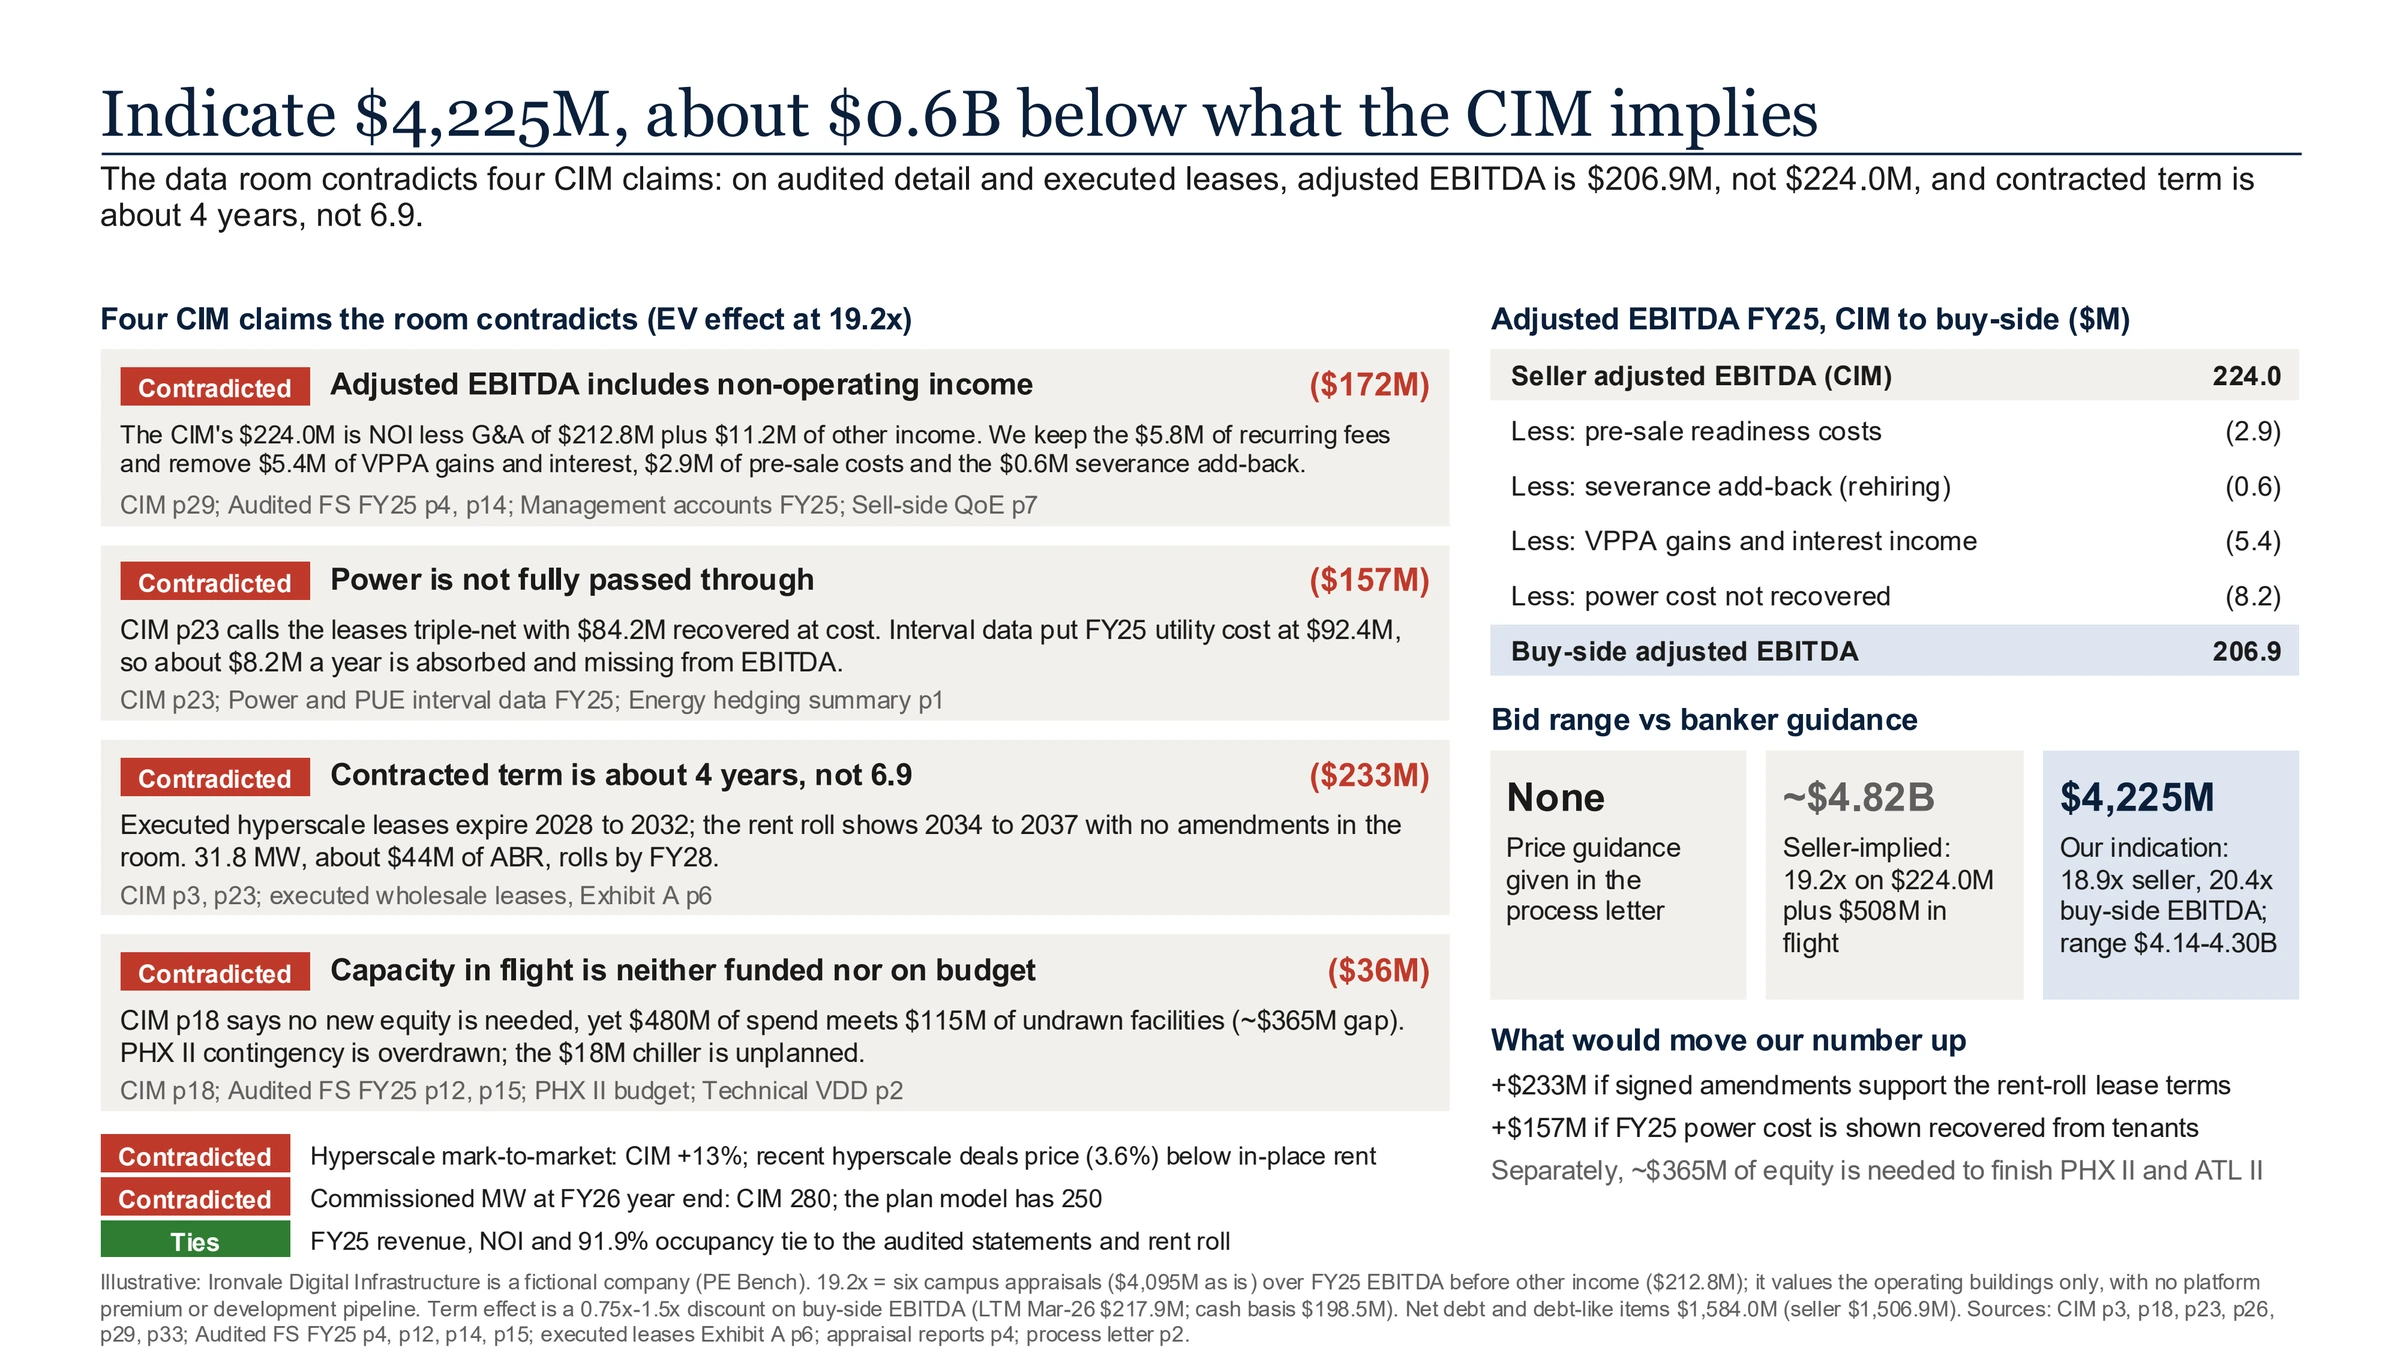
The letter’s assumptions list is what makes a bid this far under the seller’s numbers defensible. Each assumption names a document, so the second round becomes a discussion of those documents. The slide follows the shape of the investment memo example, and the returns case waits for the data room and the LBO model. If Kingsmill invites you to Phase II, the financial due diligence example picks up from there.
Takeaway: with no guidance to anchor on, the bid is $4,225M, about $0.6B below the CIM’s implied value, and every deduction starts from a document in the room.
One-page IC slide (PowerPoint)Compound’s IC slide for Project Voltaic: the four contradicted claims, seller to buyer EBITDA and the bid against what the CIM implies.Download · Free, no form IOI letter (Word)Compound’s two-page indication of interest, with the valuation basis, assumptions, financing and Phase II diligence stated, and placeholders for the purchaser’s details.Download · Free, no form